Fair and Accurate Credit Transactions Act of 2003
Public Law 108-159 · H.R. 2622 · 108th Congress · began in the House
Signed by George W. Bush (R) on Dec 4, 2003 · Finance and Financial Sector
Sponsor: Rep. Spencer Bachus (R-AL-6)
Cosponsors (58): Rep. Darlene Hooley, Rep. Judy Biggert,
Passage votesYeaNay
- HouseRecorded vote: 379 yea, 49 nay379–49
- SenateUnanimous consent
Data notes
The final version of the law, as each chamber passed it. A chamber that passed it by voice vote or unanimous consent has no count. “Method not stated” means the record does not say how the chamber voted. Where the record has a member-by-member vote, the “Who voted for it” section shows who voted yea.
Summary
The Congressional Research Service’s plain-language summary of what the law does.
Fair and Accurate Credit Transactions Act of 2003 - (Sec. 3) Requires the Board of Governors of the Federal Reserve System (Board) and the Federal Trade Commission (FTC) to jointly prescribe final regulations that establish effective dates for this Act before the end of the two-month period beginning on the date of the enactment of this Act.
States that in no case shall the effective date be later than ten months after the date of issuance of such regulations in final form.
Title I: Identity Theft Prevention and Credit History Restoration - Subtitle A: Identity Theft Prevention - (Sec.111) Amends the Fair Credit Reporting Act (FCRA) to define active duty military consumer as a consumer in military service who: (1) is on active duty or is a reservist performing duty under a call or order to active duty; and (2) is assigned to service away from the consumer's usual duty station.
Defines fraud alert and active duty alert as a statement in the consumer's file that: (1) notifies all prospective users of a consumer report that the consumer may be a victim of fraud, including identity theft, or is an active duty military consumer, as applicable; and (2) is presented in a manner that facilitates a clear and conspicuous view of the statement by any person requesting such report.
Defines identity theft report as one: (1) that alleges an identity theft; (2) that is filed by a consumer with an appropriate Federal, State, or local government agency, including the U.S. Postal Inspection Service and any law enforcement agency; and (3) the filing of which subjects the person filing the report to criminal penalties relating to the filing of false information if, in fact, the information in the report is false.
Defines reseller as a consumer reporting agency that: (1) assembles and merges information contained in the database of another consumer reporting agency or multiple consumer reporting agencies concerning any consumer for purposes of furnishing such information to any third party; and (2) does not maintain a database of the assembled or merged information from which new consumer reports are produced.
(Sec. 112) Requires a consumer reporting agency, upon consumer good faith allegation and direct request, to include a fraud alert in the consumer's file for at least 90 days (one-call fraud alert) and provide that alert along with any credit score generated in using that file. Requires the agency to inform the consumer that the consumer may request a free copy of the consumer's file.
Requires a consumer reporting agency, upon the request of a consumer who files an identity theft report, or upon receipt of a properly completed copy of a Federal Trade Commission (FTC)-developed and standardized affidavit of identity theft, to: (1) include a fraud report in the consumer's file for seven years (unless the consumer requests its removal); and (2) for five years exclude the consumer from any list provided to a third party to offer credit or insurance to the consumer as part of a transaction the consumer has not initiated.
Requires a consumer reporting agency to inform the consumer that the consumer may request two free copies of the consumer's file containing the fraud alert.
Requires a consumer reporting agency, upon active duty military consumer request, to include an active duty alert in the consumer's file for at least 12 months, including any credit score generated in using that file, (unless the consumer requests its removal), and exclude the consumer for a the two-year period from any list provided to a third party to offer credit or insurance to the consumer as part of a transaction the consumer has not initiated.
Requires a consumer reporting agency to refer such fraud alert or an active duty alert to other consumer reporting agencies.
Requires a reseller to reconvey such fraud alerts.
Prescribes: (1) requirements for initial and active duty alerts; and (2) sets forth limitations on the use of information for credit extensions by the user of a consumer credit report.
(Sec. 113) Mandates truncation of credit card and debit card numbers, with printing of no more than the last five digits.
(Sec. 114) Prescribes guidelines under which the Federal banking agencies, the National Credit Union Administration (NCUA), and the Federal Trade Commission (FTC) are directed to establish guidelines and prescribe regulations for financial institutions and creditors regarding identity theft.
(Sec. 115 ) Requires a consumer reporting agency, upon consumer request for nondisclosure of the number, to truncate a consumer's social security or similar identification number by removing the first five digits.
Subtitle B: Protection and Restoration of Identity Theft Victim Credit History - (Sec. 151) Directs the FTC to prepare a model summary of consumer rights regarding the procedures for remedying the effects of fraud or identity theft involving credit, electronic funds transfers, or accounts or transactions at or with a financial institution or other creditor.
Prescribes procedural guidelines under which a business entity, upon victim request, must provide a copy of the business records evidencing a transaction alleged to be a result of identity theft to the victim and to any law enforcement agency or officer specified by the victim, or investigating the identity theft.
Requires the FTC to implement a public education campaign on identity theft.
Sec. 152) Requires a consumer reporting agency to block the reporting of information that the consumer alleges resulted from identity theft. Cites circumstances under which such agency may decline to block, or may rescind any block of information.
Prescribes special rules governing resellers or verification companies after they have been notified of information in a consumer's file resulting from identify theft.
(Sec. 153) Prescribes guidelines for: (1) coordination of consumer complaint investigations; (2) prevention of repollution of consumer reports; and (3) debt collector communications concerning identity theft.
(Sec. 156) Extends the statute of limitations for civil liability for violations of FCRA from two to five years after the date on which the violation occurs (but not later than two years after the violation is discovered).
(Sec. 157) Directs the Secretary of the Treasury to study and report to Congress on the use of biometrics and similar technologies to reduce identity theft.
Title II: Improvements in Use of and Consumer Access to Credit Information - (Sec. 211) Requires certain nationwide consumer reporting agencies to furnish free credit reports upon consumer request once during any 12-month period.
Directs the FTC to prescribe regulations: (1) requiring certain nationwide specialty consumer reporting agencies to establish a streamlined process for consumer requests for certain consumer reports, including a toll-free telephone number; and (2) preventing a consumer reporting agency from evading treatment as a consumer reporting agency through the use of specified corporate or technological circumventions.
Revises requirements for consumer reporting agency disclosure to a consumer of a summary of consumer rights. Requires the FTC to prepare a model summary of such rights, including the right to obtain and dispute information in a consumer report, and to obtain credit scores.
(Sec. 212) Requires both consumer reporting agencies and users of credit scores who make extensions of credit for home buyers to: (1) disclose to the consumer the availability of credit scores in connection with a credit application secured by a dwelling; and (2) furnish a statement indicating that the information and credit scoring model may be different than that used by the lender.
Permits a consumer reporting agency to charge a fee, determined by the FTC for providing such information.
States that if a key factor that adversely affects the credit score of a consumer consists of the number of enquiries made with respect to a consumer report, that factor must included in the disclosure.
Requires certain mortgage lenders to disclose credit scores in connection with a consumer loan secured by 1 - 4 units of residential real property. Prescribes procedural guidelines governing such disclosures, including: (1) those governing automated underwriting systems; (2) credit scores not obtained from a consumer reporting agency; and (3) home loan applicants.
Declares void any contract provision prohibiting such mandatory disclosures. Shields lenders from liability for making mandatory disclosure of a credit score.
(Sec. 213) Extends from two years to five years the effective period during which consumers may opt-out of prescreened lists for marketing credit or insurance solicitations.
Instructs the FTC to publicize and conspicuously post on its website any address and the toll-free telephone number established as part of the system to notify consumers to opt out of such prescreened lists.
Instructs the Board to study and report to Congress on: (1) the ability of consumers to avoid receiving written offers of credit or insurance in connection with transactions not initiated by the consumer; and (2) the potential impact that any further restrictions on providing consumers with such written offers of credit or insurance would have on consumers.
(Sec. 214) Requires affiliates who exchange consumer information for market solicitation purposes to: (1) alert the consumer of such practice; and (2) allow the consumer to prohibit permanently all solicitation for marketing purposes.
Authorizes such affiliates to allow the consumer to choose from different options to prohibit solicitations, including the types of entities and information covered and solicitation methods.
Directs the Federal banking agencies, the NCUA, and the FTC to: (1) promulgate regulations limiting affiliate sharing of consumer information for solicitation purposes; and (2) study and report to Congress on consumer information sharing by users of consumer reports, including financial institution affiliates.
(Sec. 215) Requires the FTC to study and report to Congress on: (1) the effects of the use of credit scores and credit-based insurance scores upon the availability and affordability of financial products and services; (2) the correlation between the factors considered by credit score systems and the quantifiable risks and actual losses experienced by businesses; (3) the extent to which the use of credit scoring models, credit scores, and credit-based insurance scores impact on the availability and affordability of credit and insurance; and (4) the extent to which credit scoring systems are used by businesses, the factors considered by such systems, and the effects of variables which are not considered by such systems.
(Sec. 216) Directs the Federal banking agencies, the NCUA, the FTC, and the SEC to issue final regulations requiring proper disposal of consumer information or any compilation of it that is derived from consumer reports for a business purpose.
(Sec. 217) Requires certain financial institutions to provide written notice to the consumer if they furnish negative information to a consumer reporting agency regarding credit extended to such consumer.
Prescribes implementation guidelines.
Title III: Enhancing the Accuracy of Consumer Report Information - (Sec. 311) Prescribes guidelines requiring certain persons who grant credit based upon consumer reports to notify the consumer if the credit terms are materially less favorable than the most favorable terms available to a substantial proportion of consumers (risk-based pricing notice).
Declares that no person shall be liable for failure to perform such notification duties if, at the time of failure, that person maintained reasonable policies and procedures to comply with the duties. Denies a consumer any civil action for negligent or willful noncompliance by any person with such duties. Declares enforcement of this requirement rests exclusively with the administrative enforcement powers of designated Federal agencies.
Prohibits enactment of any State law imposing a requirement or prohibition relating to the duties of users of consumer reports to provide notice with respect to terms in certain credit transactions. (Thus precludes enactment of State consumer protection laws that may be more stringent than Federal law).
(Sec. 312) Directs the Federal banking agencies, the NCUA, and the FTC to coordinate regulations governing the accuracy and integrity of information provided by furnishers of consumer information to consumer reporting agencies.
Directs the Federal banking agencies, the NCUA, and the FTC to jointly prescribe regulations identifying the circumstances under which a furnisher must reinvestigate a dispute concerning the accuracy of information contained in a consumer report on the consumer, based upon direct consumer request. Prescribes procedural guidelines.
(Sec. 313) Prescribes guidelines for: (1) FTC treatment of consumer complaints of incomplete or inaccurate information maintained by a consumer reporting agency; and (2) transmission of such complaints to the agency.
Directs the Board and the FTC to study jointly and report to Congress on how consumer reporting agencies and furnishers of consumer information to those agencies comply with statutory procedures, time lines, and requirements for the prompt investigation of the disputed accuracy of consumer information, the completeness of the information provided to consumer reporting agencies, and the prompt correction or deletion of inaccurate, incomplete, or non-verifiable information.
(Sec. 314 ) Requires consumer reporting agencies which determine, upon reinvestigation, that information was inaccurate, incomplete, or unverified to promptly notify the information furnisher of such action. Requires information furnishers in such instances to promptly delete or modify such information.
(Sec. 315 ) Requires a consumer reporting agency to notify consumer report users whenever the consumer address contained in a report differs substantially from that provided by the user when it requested the report.
(Sec. 316 ) Sets forth reinvestigation requirements for resellers notified of disputed consumer information.
(Sec. 317) Revises the requirement that a consumer reporting agency reinvestigate disputed information to require a reasonable reinvestigation to determine whether the disputed information is inaccurate.
(Sec. 318) Directs the FTC to study and report to Congress on a cost-benefit analysis of ways to improve the operation of FCRA, in particular: (1) the efficacy of increasing the number of points of identifying information a credit reporting agency must match to ensure that a consumer is the correct individual to whom a credit report relates before releasing the report to a user; (2) mandatory notification of consumers when negative information has been added to their credit reports; (3) the effects of requiring that a consumer experiencing an adverse action receive a copy of the same credit report on which the creditor relied in taking the adverse action; (4) any common financial transactions not generally reported to consumer reporting agencies which would provide useful information in determining creditworthiness; and (5) any actions that might be taken within a voluntary reporting system to encourage the reporting of those types of transactions not generally reported.
(Sec. 319 ) Directs the FTC to report biennially to Congress on the accuracy and completeness of information prepared or maintained by consumer reporting agencies, and methods for improving them.
Title IV: Limiting the Use and Sharing of Medical Information in the Financial System - (Sec. 411) Revises the requirement for specific affirmative consumer consent (opt-in) regarding the use and sharing of medical information by consumer reporting agencies for employment or insurance purposes. States that medical information shall not be excluded from credit reports shared among affiliates unless it is prohibited by this title.
Directs the Federal banking agencies and the NCUA to prescribe regulations limiting the use of such medical information.
(Sec. 412) Requires information furnishers whose primary business is providing medical services, products, or devices to notify any credit reporting agency to which they furnish consumer information that they are medical information furnishers, for purposes of compliance with medical information coding requirements.
Prohibits a consumer reporting agency from including in any consumer report the name, address, and telephone number of any medical information furnisher except in code, unless the report is provided to an insurance company for other than property and casualty insurance purposes.
Requires the FTC, if a furnisher of information fails to comply with requirements for the coding of trade names, to take action, including issuance of guidelines, to ensure the furnisher's compliance with such requirements.
Title V: Financial Literacy and Education Improvement - Financial Literacy and Education Improvement Act - (Sec. 513) Establishes the Financial Literacy and Education Commission to: (1) improve Federal financial literacy and education programs, grants, and materials; (2) establish a website and a toll-free telephone number for the public; (3) disseminate public education materials; (4) develop a national strategy promoting basic financial literacy and education at the State and local level; and (5) report annually to Congress on its activities in a document entitled the "Strategy for Assuring Financial Empowerment (SAFE Strategy)" .
(Sec. 515) Authorizes the Commission to take any action to develop and promote financial literacy and education materials in languages other than English.
(Sec. 517) Directs the Comptroller General to study and report to Congress on: (1) the effectiveness of the Commission in promoting financial literacy and education; and (2) the extent of consumers' knowledge and awareness of credit reports, credit scores, the dispute resolution process, and methods for improving financial literacy among consumers.
(Sec. 518) Directs the Secretary of the Treasury, after reviewing Commission recommendations, to develop and conduct a pilot national public service multimedia campaign as part of the national strategy to enhance the state of financial literacy and education in the United States. Authorizes appropriations for FY 2004 through 2006 for such campaign.
(Sec. 519 ) Authorizes appropriations to the Commission.
Title VI: Protecting Employee Misconduct Investigations - (Sec. 611 ) Amends FCRA to exclude from consumer disclosure requirements certain communications made to an employer concerning employee misconduct.
Mandates disclosure to the consumer of a summary containing the nature and substance of a communication which forms the basis of an adverse action regarding an employee misconduct investigation. States that sources of the information acquired solely for use in preparing what would otherwise be an investigative consumer report need not be disclosed.
Title VII: Relation to State Law - (Sec. 711) Repeals the termination after January 1, 2004, of Federal preemption of State law by FCRA (thus extending such Federal preemption indefinitely).
Title VIII: Miscellaneous - (Sec. 811) Makes clerical and technical amendments to FCRA.
Who voted for it
Every House member of the 108th Congress on the ideology compass. Highlighted: the 379 who voted yea on final passage. Faded: everyone else, including those who voted nay, did not vote, or had not yet taken office.
379 yea49 nay6 present or did not vote
Democrats who voted yea(154)
 Rep. John LewisD-GA-5
 Rep. Michael CapuanoD-MA-8
 Rep. Alcee HastingsD-FL-23
 Rep. James OberstarD-MN-8
 Rep. Donald PayneD-NJ-10
 Rep. Maurice HincheyD-NY-22
 Rep. Tammy BaldwinD-WI-2
 Rep. Jim McGovernD-MA-3
 Rep. John TierneyD-MA-6
 Rep. Barney FrankD-MA-4
 Rep. Nydia VelázquezD-NY-12
- Rep. Stephanie JonesD-OH-11
 Rep. Ed TownsD-NY-10
 Rep. Wm. ClayD-MO-1
 Rep. Mel WattD-NC-12
- Rep. Julia CarsonD-IN-7
 Rep. Carolyn KilpatrickD-MI-13
 Rep. Bennie ThompsonD-MS-2
 Rep. Sheila Jackson LeeD-TX-18
 Rep. Charlie RangelD-NY-15
 Rep. Rush HoltD-NJ-12
 Rep. Tom UdallD-NM-3
 Rep. Bobby ScottD-VA-3
- Rep. Martin SaboD-MN-5
 Rep. Eddie JohnsonD-TX-30
 Rep. Rosa DeLauroD-CT-3
 Rep. Frank PalloneD-NJ-6
 Rep. José SerranoD-NY-16
 Rep. Ed PastorD-AZ-4
- Rep. Frank BallanceD-NC-1
 Rep. Elijah CummingsD-MD-7
 Rep. Diana DeGetteD-CO-1
- Rep. Jerry KleczkaD-WI-4
 Rep. Chaka FattahD-PA-2
 Rep. Jim ClyburnD-SC-6
 Rep. John LarsonD-CT-1
 Rep. Earl BlumenauerD-OR-3
 Rep. Lois CappsD-CA-23
 Rep. Richard NealD-MA-2
 Rep. Dave ObeyD-WI-7
 Rep. Marcy KapturD-OH-9
 Rep. Patrick KennedyD-RI-1
 Rep. Tom AllenD-ME-1
 Rep. Betty McCollumD-MN-4
 Rep. Corrine BrownD-FL-3
- Rep. Ted StricklandD-OH-6
 Rep. Mark UdallD-CO-2
 Rep. Robert BradyD-PA-1
 Rep. Gary AckermanD-NY-5
- Rep. Marty MeehanD-MA-5
 Rep. Tim RyanD-OH-17
 Rep. Robert WexlerD-FL-19
 Rep. Chris Van HollenD-MD-8
 Rep. Anthony WeinerD-NY-9
 Rep. Brad ShermanD-CA-27
 Rep. Carolyn MaloneyD-NY-14
 Rep. Peter ViscloskyD-IN-1
- Rep. Karen McCarthyD-MO-5
 Rep. Brian BairdD-WA-3
 Rep. John DingellD-MI-15
 Rep. Neil AbercrombieD-HI-1
 Rep. Bart StupakD-MI-1
 Rep. Rahm EmanuelD-IL-5
 Rep. William JeffersonD-LA-2
 Rep. Rob AndrewsD-NJ-1
 Rep. Michael McNultyD-NY-21
 Rep. Kendrick MeekD-FL-17
 Rep. Jay InsleeD-WA-1
 Rep. Eliot EngelD-NY-17
 Rep. Rick LarsenD-WA-2
 Rep. Ciro RodriguezD-TX-28
 Rep. Gregory MeeksD-NY-6
 Rep. Dale KildeeD-MI-5
- Rep. Denise MajetteD-GA-4
 Rep. Jim LangevinD-RI-2
 Rep. Bill PascrellD-NJ-8
 Rep. Steny HoyerD-MD-5
 Rep. Sander LevinD-MI-12
 Rep. Timothy BishopD-NY-1
 Rep. Brad MillerD-NC-13
 Rep. Steven RothmanD-NJ-9
 Rep. Bob MenendezD-NJ-13
 Rep. Joe CrowleyD-NY-7
- Rep. Harold FordD-TN-9
- Rep. Joseph HoeffelD-PA-13
- Rep. Chris BellD-TX-25
 Rep. Nita LoweyD-NY-18
 Rep. Michael DoyleD-PA-14
- Rep. Peter DeutschD-FL-20
 Rep. Nick RahallD-WV-3
 Rep. Gene GreenD-TX-29
 Rep. Nick LampsonD-TX-9
 Rep. Shelley BerkleyD-NV-1
 Rep. Stephen LynchD-MA-9
 Rep. David WuD-OR-1
 Rep. Joe BacaD-CA-43
 Rep. Marion BerryD-AR-1
 Rep. Jerry CostelloD-IL-12
- Rep. Albert WynnD-MD-4
 Rep. Benjamin CardinD-MD-3
 Rep. Carolyn McCarthyD-NY-4
 Rep. Michael MichaudD-ME-2
 Rep. Paul KanjorskiD-PA-11
- Rep. Martin FrostD-TX-24
 Rep. David PriceD-NC-4
 Rep. Norm DicksD-WA-6
 Rep. Artur DavisD-AL-7
 Rep. Bob EtheridgeD-NC-2
 Rep. Rubén HinojosaD-TX-15
 Rep. John SprattD-SC-5
 Rep. Steve IsraelD-NY-2
 Rep. Charlie GonzalezD-TX-20
 Rep. Jim MoranD-VA-8
 Rep. Darlene HooleyD-OR-5
- Rep. Jim DavisD-FL-11
 Rep. Alan MollohanD-WV-1
 Rep. Ron KindD-WI-3
 Rep. Mike RossD-AR-4
 Rep. Silvestre ReyesD-TX-16
- Rep. Max SandlinD-TX-1
 Rep. Baron HillD-IN-9
 Rep. Jim CooperD-TN-5
 Rep. Leonard BoswellD-IA-3
 Rep. Dennis MooreD-KS-3
 Rep. Sanford BishopD-GA-2
 Rep. Vic SnyderD-AR-2
 Rep. Solomon OrtizD-TX-27
 Rep. Adam SmithD-WA-9
 Rep. John TannerD-TN-8
 Rep. Dennis CardozaD-CA-18
 Rep. Mike McIntyreD-NC-7
 Rep. Ed CaseD-HI-2
 Rep. Earl PomeroyD-ND
 Rep. Rick BoucherD-VA-9
 Rep. David ScottD-GA-13
 Rep. Tim HoldenD-PA-17
 Rep. Ike SkeltonD-MO-4
- Rep. Jim TurnerD-TX-2
 Rep. John MurthaD-PA-12
- Rep. William LipinskiD-IL-3
 Rep. Chet EdwardsD-TX-11
- Rep. Cal DooleyD-CA-20
- Rep. Brad CarsonD-OK-2
 Rep. Lincoln DavisD-TN-4
 Rep. Gene TaylorD-MS-4
 Rep. Jim MarshallD-GA-3
 Rep. Allen BoydD-FL-2
 Rep. Jim MathesonD-UT-2
- Rep. Chris JohnD-LA-7
 Rep. Collin PetersonD-MN-7
- Rep. Charlie StenholmD-TX-17
- Rep. Ken LucasD-KY-4
 Rep. Rodney AlexanderD-LA-5
 Rep. Bud CramerD-AL-5
Republicans who voted yea(225)
- Rep. Jim LeachR-IA-2
 Rep. Michael CastleR-DE
 Rep. Christopher ShaysR-CT-4
 Rep. Timothy JohnsonR-IL-15
- Rep. Doug BereuterR-NE-1
- Rep. Rob SimmonsR-CT-2
- Rep. Sherry BoehlertR-NY-24
 Rep. Chris SmithR-NJ-4
 Rep. Heather WilsonR-NM-1
 Rep. Frank LoBiondoR-NJ-2
 Rep. John McHughR-NY-23
 Rep. Fred UptonR-MI-6
 Rep. Steven LaTouretteR-OH-14
- Rep. Jack QuinnR-NY-27
 Rep. Ray LaHoodR-IL-18
- Rep. Sue KellyR-NY-19
 Rep. Jim SaxtonR-NJ-3
 Rep. Shelley CapitoR-WV-2
- Rep. Ernie FletcherR-KY-6
- Rep. Curt WeldonR-PA-7
- Rep. John SweeneyR-NY-20
- Rep. Amo HoughtonR-NY-29
 Rep. Pete KingR-NY-3
 Rep. Jon PorterR-NV-3
 Rep. Jim GerlachR-PA-6
 Rep. Vernon EhlersR-MI-3
 Rep. Jo Ann EmersonR-MO-8
- Rep. Bill JanklowR-SD
 Rep. Mike FergusonR-NJ-7
- Rep. Nancy JohnsonR-CT-5
 Rep. Frank WolfR-VA-10
 Rep. Phil EnglishR-PA-3
 Rep. Jim WalshR-NY-25
 Rep. Tom LathamR-IA-4
 Rep. Richard BurrR-NC-5
 Rep. Rodney FrelinghuysenR-NJ-11
 Rep. Rick RenziR-AZ-1
 Rep. Todd PlattsR-PA-19
- Rep. Bob NeyR-OH-18
- Rep. George NethercuttR-WA-5
 Rep. Mary Bono MackR-CA-45
 Rep. Mark KirkR-IL-10
- Rep. Clay ShawR-FL-22
 Rep. Ed WhitfieldR-KY-1
 Rep. Tom DavisR-VA-11
 Rep. Greg WaldenR-OR-2
 Rep. Ileana Ros-LehtinenR-FL-18
 Rep. Ralph RegulaR-OH-16
 Rep. Dave HobsonR-OH-7
- Rep. Tom OsborneR-NE-3
- Rep. Jim GreenwoodR-PA-8
 Rep. Ralph HallD-TX-4
 Rep. Tim MurphyR-PA-18
 Rep. Candice MillerR-MI-10
 Rep. Ken CalvertR-CA-44
 Rep. Wayne GilchrestR-MD-1
- Rep. Paul GillmorR-OH-5
- Rep. Jeb BradleyR-NH-1
 Rep. John PetersonR-PA-5
 Rep. Lincoln Diaz-BalartR-FL-21
 Rep. Chip PickeringR-MS-3
 Rep. Thad McCotterR-MI-11
 Rep. Deborah PryceR-OH-15
- Rep. Anne NorthupR-KY-3
 Rep. Michael TurnerR-OH-3
 Rep. Jerry LewisR-CA-41
- Rep. Don SherwoodR-PA-10
 Rep. Jerry WellerR-IL-11
 Rep. Judy BiggertR-IL-13
 Rep. W. Bill YoungR-FL-10
- Rep. Jim KolbeR-AZ-8
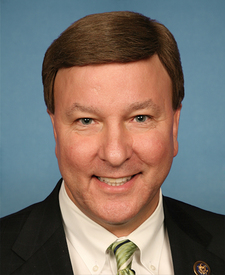 Rep. Mike RogersR-AL-3
 Rep. Don YoungR-AK
- Rep. Henry HydeR-IL-6
 Rep. Joe KnollenbergR-MI-9
 Rep. Mike SimpsonR-ID-2
 Rep. Ander CrenshawR-FL-4
 Rep. Dave CampR-MI-4
- Rep. Doug OseR-CA-3
 Rep. Hal RogersR-KY-5
 Rep. Frank LucasR-OK-3
 Rep. Ginny Brown-WaiteR-FL-5
 Rep. Rob PortmanR-OH-2
 Rep. Kay GrangerR-TX-12
 Rep. Henry BrownR-SC-1
- Rep. Jim NussleR-IA-1
- Rep. Max BurnsR-GA-12
- Rep. Billy TauzinR-LA-3
- Rep. Porter GossR-FL-14
 Rep. Darrell IssaR-CA-49
 Rep. Elton GalleglyR-CA-24
- Rep. Duke CunninghamR-CA-50
 Rep. Roger WickerR-MS-1
- Rep. Bill ThomasR-CA-22
 Rep. Robert AderholtR-AL-4
- Rep. Henry BonillaR-TX-23
 Rep. Buck McKeonR-CA-25
 Rep. David DreierR-CA-26
 Rep. Jerry MoranR-KS-1
 Rep. Zach WampR-TN-3
 Rep. Devin NunesR-CA-21
 Rep. Lamar SmithR-TX-21
 Rep. Denny RehbergR-MT
- Rep. Jennifer DunnR-WA-8
 Rep. Mike RogersR-MI-8
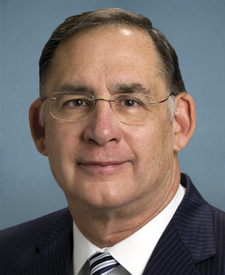 Rep. John BoozmanR-AR-3
 Rep. John MicaR-FL-7
- Rep. Michael OxleyR-OH-4
 Rep. Bill ShusterR-PA-9
 Rep. Tom ColeR-OK-4
 Rep. Thomas ReynoldsR-NY-26
 Rep. Spencer BachusR-AL-6
 Rep. Charlie BassR-NH-2
 Rep. Kenny HulshofR-MO-9
 Rep. Steve PearceR-NM-2
- Rep. Cass BallengerR-NC-10
- Rep. Bill JenkinsR-TN-1
 Rep. Jo BonnerR-AL-1
 Rep. Ron LewisR-KY-2
 Rep. Doc HastingsR-WA-4
- Rep. Michael BilirakisR-FL-9
 Rep. Robin HayesR-NC-8
 Rep. Adam PutnamR-FL-12
 Rep. Pat TiberiR-OH-12
 Rep. Jim McCreryR-LA-4
 Rep. Mark SouderR-IN-3
 Rep. Duncan HunterR-CA-52
- Rep. Richard PomboR-CA-11
- Rep. Jo Ann DavisR-VA-1
- Rep. Richard BakerR-LA-6
 Rep. Steve BuyerR-IN-4
- Rep. Katherine HarrisR-FL-13
 Rep. Virgil GoodeR-VA-5
 Rep. Randy ForbesR-VA-4
- Rep. Charles TaylorR-NC-11
 Rep. Todd TiahrtR-KS-4
 Rep. Dave WeldonR-FL-15
 Rep. John DoolittleR-CA-4
 Rep. John BoehnerR-OH-8
 Rep. George RadanovichR-CA-19
- Rep. Ernest IstookR-OK-5
- Rep. Melissa HartR-PA-4
 Rep. Roy BluntR-MO-7
 Rep. Walter JonesR-NC-3
 Rep. John ShimkusR-IL-19
 Rep. Dan BurtonR-IN-5
 Rep. Bob GoodlatteR-VA-6
 Rep. Jim RamstadR-MN-3
- Rep. Ed SchrockR-VA-2
 Rep. Sam GravesR-MO-6
 Rep. John KlineR-MN-2
 Rep. Phil GingreyR-GA-11
 Rep. Vito FossellaR-NY-13
- Rep. Tom DeLayR-TX-22
- Rep. Mark GreenR-WI-8
 Rep. Ric KellerR-FL-8
 Rep. Terry EverettR-AL-2
- Rep. Jim RyunR-KS-2
 Rep. Eric CantorR-VA-7
 Rep. Mario Diaz-BalartR-FL-25
 Rep. John CarterR-TX-31
 Rep. John SullivanR-OK-1
 Rep. David VitterR-LA-1
 Rep. Lee TerryR-NE-2
- Rep. Scott McInnisR-CO-3
- Rep. Jim GibbonsR-NV-2
 Rep. Donald ManzulloR-IL-16
 Rep. Rob BishopR-UT-1
- Rep. Bob BeauprezR-CO-7
 Rep. Jack KingstonR-GA-1
 Rep. Joe BartonR-TX-6
 Rep. Pete HoekstraR-MI-2
 Rep. Johnny IsaksonR-GA-6
- Rep. J.D. HayworthR-AZ-5
- Rep. Mark KennedyR-MN-6
- Rep. Chris ChocolaR-IN-2
 Rep. Tom PetriR-WI-6
 Rep. John CulbersonR-TX-7
 Rep. John LinderR-GA-7
 Rep. Gary MillerR-CA-42
 Rep. Mac ThornberryR-TX-13
 Rep. Randy NeugebauerR-TX-19
 Rep. Michael BurgessR-TX-26
 Rep. Joe WilsonR-SC-2
- Rep. Gil GutknechtR-MN-1
 Rep. Kevin BradyR-TX-8
 Rep. Joseph PittsR-PA-16
 Rep. Howard CobleR-NC-6
 Rep. Steve ChabotR-OH-1
- Rep. Christopher CoxR-CA-48
 Rep. Paul RyanR-WI-1
 Rep. Barbara CubinR-WY
 Rep. Marsha BlackburnR-TN-7
 Rep. Wally HergerR-CA-2
 Rep. Pete SessionsR-TX-32
 Rep. Chris CannonR-UT-3
- Rep. Charlie NorwoodR-GA-9
- Rep. Phil CraneR-IL-8
 Rep. Mac CollinsR-GA-8
 Rep. Jim DeMintR-SC-4
 Rep. Sue MyrickR-NC-9
 Rep. Nathan DealR-GA-10
 Rep. Sam JohnsonR-TX-3
- Rep. John HostettlerR-IN-8
 Rep. Steve KingR-IA-5
 Rep. Marilyn MusgraveR-CO-4
 Rep. Todd AkinR-MO-2
 Rep. J. Gresham BarrettR-SC-3
- Rep. Nick SmithR-MI-7
 Rep. Scott GarrettR-NJ-5
 Rep. Cliff StearnsR-FL-6
 Rep. Mike PenceR-IN-6
 Rep. Tom FeeneyR-FL-24
- Rep. Joel HefleyR-CO-5
 Rep. Dana RohrabacherR-CA-46
 Rep. Jeb HensarlingR-TX-5
 Rep. Tom TancredoR-CO-6
 Rep. Ed RoyceR-CA-40
 Rep. Roscoe BartlettR-MD-6
- Rep. Butch OtterR-ID-1
 Rep. James SensenbrennerR-WI-5
 Rep. Jeff MillerR-FL-1
 Rep. Pat ToomeyR-PA-15
 Rep. John ShadeggR-AZ-3
 Rep. Trent FranksR-AZ-2
Data notes
The House’s recorded vote on the final version of the law (roll call 665 in Voteview), matched to the vote the record cites and checked against its totals. Positions are each member’s DW-NOMINATE score for that Congress, as on the Ideology page; left to right is more liberal to more conservative. Paired and announced yea votes count as yea. Lists follow the compass, most liberal first. A name links to a profile only for members of the current Congress. A law passed by voice vote or unanimous consent has no member list, and neither does a vote Voteview has not yet recorded.
Committees
The committees the bill was sent to, and what each did with it.
 Financial Services Committee · House · hearings by, markup by, referred to, reported bySubcommittee: Consumer Protection and Financial Institutions Subcommittee
Data notes
A committee links to its page only where it exists in the current Congress; older and renamed committees are named without a link.
Related bills
3 bills the Library of Congress relates to this one.
H.R. 2617Related bill
Consumer Identity and Information Security Act of 2003
H.Res. 360Procedurally-related
Providing for consideration of the bill (H.R. 2622) to amend the Fair Credit Reporting Act, to prevent identity theft, improve resolution of consumer disputes, improve the accuracy of consumer records, make improvements…
S. 1753Procedurally-relatedRelated billRelated document
National Consumer Credit Reporting System Improvement Act of 2003
Data notes
Related bills are identified by the Congressional Research Service, the House and the Senate: companion and identical bills, bills with similar text, bills that were folded into this law, and rules that brought it to the floor. A bill that is itself a public law in this site’s data links here; the others link to Congress.gov.
Timeline
From introduction to signing, newest first: the committees, the floor and the president. 74 actions.
- Dec 4, 2003Became lawBecame law · Became Public Law No: 108-159.
- Became lawBecame law · Signed by President.
- Dec 3, 2003FloorFloor · Presented to President.
- Nov 25, 2003FloorFloor · Message on Senate action sent to the House.
- Nov 22, 2003Resolving differencesResolving differences · Senate agreed to conference report by Unanimous Consent.
- Resolving differencesResolving differences · Conference report agreed to in Senate: Senate agreed to conference report by Unanimous Consent.
- Resolving differencesResolving differences · Conference papers: message on House action held at the desk in Senate.
- Nov 21, 2003Resolving differencesResolving differences · On motion to suspend the rules and agree to the conference report Agreed to by the Yeas and Nays: (2/3 required): 379 - 49, 1 Present (Roll no. 667).House roll call 667
- Resolving differencesResolving differences · Motions to reconsider laid on the table Agreed to without objection.
- Resolving differencesResolving differences · Conference report agreed to in House: On motion to suspend the rules and agree to the conference report Agreed to by the Yeas and Nays: (2/3 required): 379 - 49, 1 Present (Roll no. 667).House roll call 667
- Resolving differencesResolving differences · The House proceeded to consider the conference report H.Rept. 108-396 as unfinished business.
- Resolving differencesResolving differences · Mr. Oxley moved to suspend the rules and agree to the conference report, H. Rept. 108-396.
- Resolving differencesResolving differences · Conference report H. Rept. 108-396 filed.
- Resolving differencesResolving differences · Conference report filed: Conference report H. Rept. 108-396 filed.
- Resolving differencesResolving differences · Conference papers: Senate report and manager's statement held at the desk in Senate.
- FloorFloor · POSTPONED PROCEEDINGS - At the conclusion of debate on the motion to suspend the rules and agree to the conference report on H.R. 2622, the Chair put the question on adoption of the motion and by voice vote, announced that the ayes had prevailed. Mr. Sanders demanded the yeas an…
- FloorFloor · DEBATE - The House proceeded with forty minutes of debate on the motion to suspend the rules and agree to the conference report on H.R. 2622.
- Nov 6, 2003Resolving differencesResolving differences · The Speaker appointed conferees for consideration of the House bill and the Senate amendment, and modifications committed to conference: Oxley, Bereuter, Bachus, Castle, Royce, Ney, Kelly, Gillmor, LaTourette, Biggert, Sessions, Frank (MA), Kanjorski, Sanders, Waters, Watt, Guti…
- Resolving differencesResolving differences · Motion to reconsider laid on the table Agreed to without objection.
- Resolving differencesResolving differences · On motion that the House instruct conferees Agreed to by voice vote.
- Resolving differencesResolving differences · The previous question was ordered without objection.
- Resolving differencesResolving differences · Mr. Frank (MA) moved that the House instruct conferees.
- Resolving differencesResolving differences · On motion that the House disagree to the Senate amendment, and agree to a conference Agreed to by voice vote.
- Resolving differencesResolving differences · Mr. Oxley moved that the House disagree to the Senate amendment, and agree to a conference.
- FloorFloor · DEBATE - The House proceeded with one hour of debate on the Frank motion to instruct conferees.
- FloorFloor · DEBATE - The House proceeded with one hour of debate on the motion.
- Nov 5, 2003Resolving differencesResolving differences · Senate insists on its amendment, asks for a conference, appoints conferees Shelby; Bennett; Allard; Enzi; Sarbanes; Dodd; Johnson.
- FloorFloor · Message on Senate action sent to the House.
- FloorFloor · See also S. 1753.
- FloorFloor · Passed Senate with an amendment by Yea-Nay Vote. 95 - 2. Record Vote Number: 437.Senate roll call 437
Data notes
Every action the Library of Congress lists for the bill, from introduction to signing, plus the dated committee hearings. The source lists many steps twice (the chamber’s own entry and the Library of Congress copy, or a presidential and a became-law entry with the same words); those are shown once. Amendments are listed in their own section.
Amendments
11 amendments offered to the bill, with the last recorded step of each.
- Withdrawn
H.Amdt. 394HouseRep. Ellen TauscherD-CA-10· offered Sep 10, 2003Withdrawn
Sep 10, 2003: By unanimous consent, the Tauscher amendment was withdrawn.
- Agreed to
H.Amdt. 393HouseRep. Barney FrankD-MA-4· offered Sep 10, 2003Agreed to
An amendment numbered 6 printed in the Congressional Record to require that regional credit bureaus also be required to give consumers a free copy of their credit report each year.
Sep 10, 2003: On agreeing to the Frank (MA) amendment (A010) Agreed to by recorded vote: 235 - 186, 1 Present (Roll no. 497).
- Withdrawn
H.Amdt. 392HouseRep. Jay InsleeD-WA-1· offered Sep 10, 2003Withdrawn
An amendment numbered 3 printed in the Congressional Record.
Sep 10, 2003: By unanimous consent, the Inslee amendment was withdrawn.
- Rejected
H.Amdt. 391HouseRep. Paul KanjorskiD-PA-11· offered Sep 10, 2003Rejected
An amendment numbered 1 printed in the Congressional Record to insert a 9 year sunset provision into the bill.
Sep 10, 2003: On agreeing to the Kanjorski amendment (A008) Failed by recorded vote: 112 - 310, 1 Present (Roll no. 496).
- Withdrawn
H.Amdt. 390HouseRep. Sue KellyR-NY-19· offered Sep 10, 2003Withdrawn
An amendment numbered 16 printed in the Congressional Record to insert a new subsection providing for regulatory authority to adjust report distribution schedules in times of request spikes.
Sep 10, 2003: By unanimous consent, the Kelly amendment was withdrawn.
- Rejected
H.Amdt. 389HouseRep. Bernie SandersD-VT· offered Sep 10, 2003Rejected
An amendment numbered 4 printed in the Congressional Record to insert provisions limiting the use of consumer reports.
Sep 10, 2003: On agreeing to the Sanders amendment (A006) Failed by recorded vote: 142 - 272, 1 Present (Roll no. 495).
- Withdrawn
H.Amdt. 388HouseRep. Ed RoyceR-CA-40· offered Sep 10, 2003Withdrawn
An amendment numbered 11 printed in the Congressional Record to provide conditions in which a consumer may dispute the accuracy of information that is contained in a consumer report on the consumer prepared by a consumer reporting agency.
Sep 10, 2003: By unanimous consent, the Royce amendment was withdrawn.
- Agreed to
H.Amdt. 387HouseRep. Bob NeyR-OH-18· offered Sep 10, 2003Agreed to
An amendment numbered 12 printed in the Congressional Record which makes bill provisions regarding free credit reports and consumer access to credit scores a national standard by pre-empting any future state laws in either area.
Sep 10, 2003: On agreeing to the Ney amendment (A004) Agreed to by recorded vote: 233 - 189, 1 Present (Roll no. 498).
- Withdrawn
H.Amdt. 386HouseRep. Barbara LeeD-CA-9· offered Sep 10, 2003Withdrawn
An amendment numbered 15 printed in the Congressional Record to insert langage which exempts the California Financial Information Privacy Act, or the law of any other State that is similar to that Act, from the provisions of the bill.
Sep 10, 2003: By unanimous consent, the Lee amendment was withdrawn.
- Rejected
H.Amdt. 385HouseRep. Maxine WatersD-CA-35· offered Sep 10, 2003Rejected
An amendment numbered 8 printed in the Congressional Record to exempt certain California laws from the pre-emption provisions in the bill.
Sep 10, 2003: On agreeing to the Waters amendment (A002) Failed by voice vote.
- Agreed to
H.Amdt. 384HouseRep. Michael OxleyR-OH-4· offered Sep 10, 2003Agreed to
An amendment numbered 17 printed in the Congressional Record to make technical and conforming changes to the bill.
Sep 10, 2003: On agreeing to the Oxley amendment (A001) Agreed to by voice vote.
Data notes
Amendments offered to this bill in either chamber, as the Library of Congress records them: each with a status read from its last recorded step: agreed to, rejected, withdrawn, ruled out of order, fell with another amendment, or offered with no vote recorded (most Senate amendments are only ever offered). The wording of each amendment is the source’s. Amendments to amendments and amendments to other bills are not listed.
Official record
The bill’s full text is on Congress.gov. Data through Oct 7, 2026.