United States v. Rodgers et al.
461 U.S. 677 · No. 81-1476 · 1982 term · Burger Court
Decided May 31, 1983 · argued Dec 6, 1982
Federal taxation · Priority of federal fiscal claims: over those of the states or private entities
Majority opinion: William Brennan
The voteMajorityDissent
5–45 in the majority, 4 in dissent
4 dissents (5–4)
Reversed and remanded. United States won.
What this ruling means
Reversed and remanded: the Supreme Court overturned the decision of the U.S. Court of Appeals, Fifth Circuit and sent the case back to that court for further proceedings that follow the Supreme Court’s ruling.
United States was the petitioner, the side that asked the Supreme Court to review the case. “Won” means the Court gave that side the result it asked for.
From the Supreme Court Database. A justice who agreed with the result but not the reasoning counts in the majority.
Summary
The opening of the case’s Wikipedia article: what the case was about and what the Court held.
Wikipedia has no article on this case, so there is no summary.
Data notes
The text is Wikipedia’s (CC BY-SA 4.0), matched to the case by its citation, docket number or name and year, and is not checked against the opinion. The site keeps the article’s opening section, ending on its last full sentence. The one-sentence summary under the title is the Decisions list’s: Wikipedia’s own ruling sentence, or, tagged “AI-written”, one Claude wrote from this opening.
How the justices voted
Each justice who took part, placed by their Martin–Quinn ideology score for the 1982 term. Filled: the 5 in the majority. Hollow: the 4 in dissent. Colour is the party of the president who appointed them.
Majority(5)
 William BrennanWrote the majority opinion
 Thurgood MarshallJoined the majority
 Byron WhiteJoined the majority
 Lewis PowellJoined the majority
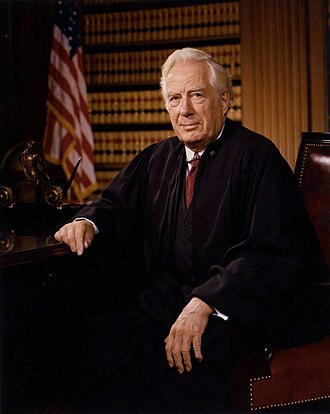 Warren BurgerJoined the majority
Dissent(4)
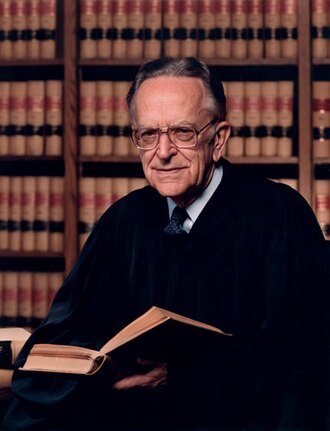 Harry BlackmunWrote a dissent
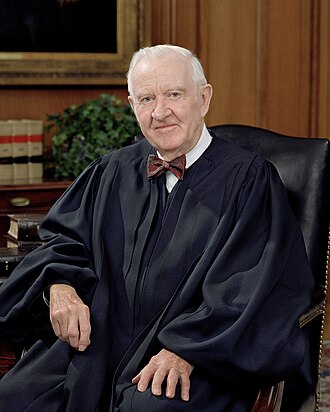 John StevensJoined a dissent
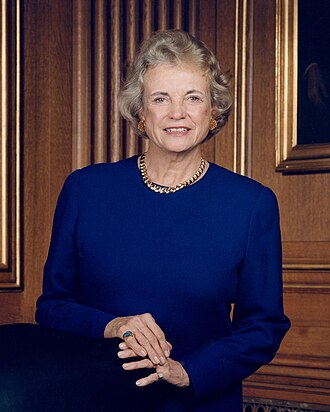 Sandra O'ConnorJoined a dissent
 William RehnquistJoined a dissent
Data notes
Each justice’s vote and what they wrote are from the justice-centered file of the Supreme Court Database. “Wrote a concurrence” means the justice sided with the majority and wrote separately; a justice who dissented in part is counted on the side they took overall. A justice who wrote nothing is listed as joining their side.
Positions are each justice’s Martin–Quinn score for the case’s term, the same scores as the Ideology page: negative is more liberal, positive more conservative. A score sums up a justice’s votes across the whole term, so it says where they usually sit, not why they voted as they did here. The median line is the Court’s median justice that term.
The parties
Who brought the case to the Court, who answered it, and how it got there.
- Petitioner
- United StatesInternal Revenue Service, Collector, Commissioner, or District Director
- Respondent
- Rodgers et al.Taxpayer or executor of taxpayer's estate, federal only
- Reached the Court by
- Certiorari (the Court chose to hear it)
- Why it was taken
- Federal appeals courts had ruled differently on the question
Data notes
The names are the two sides of the case’s title. The description under each is the Supreme Court Database’s category for that party, in its own wording. The petitioner is the side that asked the Supreme Court to review the decision below. “Why it was taken” appears only when the majority opinion says lower courts disagreed or were unsure about the question; reasons that would fit any case (“to resolve the question presented”, “an important question”) are left out.
The law at issue
The law the Court was asked to apply, and the kind of power it used to decide.
- Provision
- Internal Revenue Code and pre-IRC revenue acts
- Kind of law
- Federal Statute
- Decided by
- Statutory construction
Data notes
The Supreme Court Database codes the main constitutional provision, statute or court rule each case turned on, and the basis of the decision: judicial review of a federal or state law, interpreting a statute, supervising the lower courts, and so on. A case can rest on more than one. “Overruled” counts only where the majority opinion says so.
Timeline
What happened at the Court and how the case got there, newest first.
- May 31, 1983DecidedDecided · Decided 5–4: reversed and remanded. United States won.
- Dec 6, 1982ArguedArgued · Oral argument before the Court.
- Not datedTaken upTaken up · The Supreme Court agreed to hear the case (certiorari). Federal appeals courts had ruled differently on the question.
- Not datedCourt belowCourt below · Decided by the U.S. Court of Appeals, Fifth Circuit: unusual disposition.
- Not datedBeganBegan · The case began in the Texas Northern U.S. District Court.
Data notes
From the Supreme Court Database: the court the case began in, the court whose decision the Supreme Court reviewed and what that court did, how the case came to the Court, and the dates of argument and decision. The database does not date the steps in the lower courts. Court names are the database’s.
Other decisions on the same issue
47 other argued cases since 1946 on priority of federal fiscal claims: over those of the states or private entities, newest first.
- Lynwood D. Hall, et ux., Petitioners v. United States566 U.S. 506May 14, 2012 · 566 U.S. 506Federal taxation5–45–4 band
- United States v. Estate of Francis J. Romani et al.523 U.S. 517Apr 29, 1998 · 523 U.S. 517Federal taxation9–0Unanimous band
- United States v. Reorganized Cf&I Fabricators of Utah, Inc., et al.518 U.S. 213Jun 20, 1996 · 518 U.S. 213Federal taxation9–0Unanimous band
- United States v. Thomas R. Noland, Trustee for Debtor First Truck Lines, Inc.517 U.S. 535May 13, 1996 · 517 U.S. 535Federal taxation9–0Unanimous band
- United States by and Through Internal Revenue Service v. Bruce J. McDermott et al.507 U.S. 447Mar 24, 1993 · 507 U.S. 447Federal taxation6–36–3 band
- Harry P. Begier, Jr., etc. v. Internal Revenue Service496 U.S. 53Jun 4, 1990 · 496 U.S. 53Federal taxation9–0Unanimous band
- United States v. Ron Pair Enterprises, Inc.489 U.S. 235Feb 22, 1989 · 489 U.S. 235Federal taxation5–45–4 band
- United States v. Kimbell Foods, Inc., et al.440 U.S. 715Apr 2, 1979 · 440 U.S. 715Federal taxation9–0Unanimous band
- United States v. Sotelo et ux.436 U.S. 268May 22, 1978 · 436 U.S. 268Federal taxation5–45–4 band
- Slodov v. United States436 U.S. 238May 22, 1978 · 436 U.S. 238Federal taxation6–36–3 band
- United States v. Moore et al.423 U.S. 77Dec 2, 1975 · 423 U.S. 77Federal taxation8–0Unanimous band
- Phelps, Receiver in Bankruptcy v. United States421 U.S. 330May 19, 1975 · 421 U.S. 330Federal taxation9–0Unanimous band
- Otte, Trustee in Bankruptcy v. United States et al.419 U.S. 43Nov 19, 1974 · 419 U.S. 43Federal taxation9–0Unanimous band
- United States v. Randall, Trustee in Bankruptcy401 U.S. 513Mar 24, 1971 · 401 U.S. 513Federal taxation5–45–4 band
- United States v. Key, Trustee in Bankruptcy397 U.S. 322Mar 30, 1970 · 397 U.S. 322Federal taxation8–0Unanimous band
- United States v. Estate of Donnelly et al.397 U.S. 286Mar 23, 1970 · 397 U.S. 286Federal taxation5–36–3 band
- Joint Industry Board of the Electrical Industry et al. v. United States391 U.S. 224May 20, 1968 · 391 U.S. 224Federal taxation6–36–3 band
- United States v. Equitable Life Assurance Society of the United States384 U.S. 323Jun 6, 1966 · 384 U.S. 323Federal taxation8–18–1 band
- United States v. Speers, Trustee in Bankruptcy382 U.S. 266Dec 13, 1965 · 382 U.S. 266Federal taxation8–18–1 band
- United States v. Vermont et al.377 U.S. 351Jun 1, 1964 · 377 U.S. 351Federal taxation9–0Unanimous band
- Meyer v. United States375 U.S. 233Dec 16, 1963 · 375 U.S. 233Federal taxation6–36–3 band
- United States v. Pioneer American Insurance Co. et al.374 U.S. 84Jun 10, 1963 · 374 U.S. 84Federal taxation8–18–1 band
- United States v. Buffalo Savings Bank371 U.S. 228Jan 7, 1963 · 371 U.S. 228Federal taxation8–18–1 band
- United States v. Union Central Life Insurance Co.368 U.S. 291Dec 18, 1961 · 368 U.S. 291Federal taxation8–18–1 band
- Small Business Administration v. McClellan, Trustee364 U.S. 446Dec 5, 1960 · 364 U.S. 446Federal taxation8–18–1 band
- United States v. Hougham et al.364 U.S. 310Nov 7, 1960 · 364 U.S. 310Federal taxation7–27–2 band
- United States v. John Hancock Mutual Life Insurance Co. et al.364 U.S. 301Nov 7, 1960 · 364 U.S. 301Federal taxation9–0Unanimous band
- United States v. Durham Lumber Co. et al.363 U.S. 522Jun 20, 1960 · 363 U.S. 522Federal taxation7–27–2 band
- Aquilino et al., Doing Business As Home Maintenance Co., et al. v. United States et al.363 U.S. 509Jun 20, 1960 · 363 U.S. 509Federal taxation7–27–2 band
- United States v. Brosnan et al.363 U.S. 237Jun 13, 1960 · 363 U.S. 237Federal taxation5–45–4 band
- United States v. Scovil et al.348 U.S. 218Jan 10, 1955 · 348 U.S. 218Federal taxation8–0Unanimous band
- United States v. Liverpool & London & Globe Insurance Co., Ltd. et al.348 U.S. 215Jan 10, 1955 · 348 U.S. 215Federal taxation8–0Unanimous band
- United States v. Acri et al.348 U.S. 211Jan 10, 1955 · 348 U.S. 211Federal taxation8–0Unanimous band
- Brownell, Attorney General, Successor to the Alien Property Custodian, v. Singer347 U.S. 403Apr 5, 1954 · 347 U.S. 403Federal taxation5–36–3 band
- United States v. City of New Britain et al.347 U.S. 81Feb 1, 1954 · 347 U.S. 81Federal taxation9–0Unanimous band
- Central Bank v. United States345 U.S. 639Jun 1, 1953 · 345 U.S. 639Federal taxation4–36–3 band
- United States v. Gilbert Associates, Inc.345 U.S. 361Apr 6, 1953 · 345 U.S. 361Federal taxation7–27–2 band
- Orvis et al. v. Brownell, Attorney General, Successor to the Alien Property Custodian345 U.S. 183Mar 16, 1953 · 345 U.S. 183Federal taxation6–27–2 band
- Nathanson, Trustee in Bankruptcy, v. National Labor Relations Board344 U.S. 25Nov 10, 1952 · 344 U.S. 25Federal taxation7–27–2 band
- Zittman v. McGRATH, Attorney General, Successor to the Alien Property Custodian341 U.S. 471May 28, 1951 · 341 U.S. 471Federal taxation8–0Unanimous band
- Zittman v. McGRATH, Attorney General, Successor to the Alien Property Custodian341 U.S. 446May 28, 1951 · 341 U.S. 446Federal taxation6–27–2 band
- United States v. Security Trust & Savings Bank, Executor, et al.340 U.S. 47Nov 13, 1950 · 340 U.S. 47Federal taxation9–0Unanimous band
- Lyon, Superintendent of Banks, v. Singer339 U.S. 841Jun 5, 1950 · 339 U.S. 841Federal taxation8–18–1 band
- Goggin, Trustee in Bankruptcy, v. Division of Labor Law Enforcement of California336 U.S. 118Jan 31, 1949 · 336 U.S. 118Federal taxation9–0Unanimous band
- Massachusetts et al. v. United States333 U.S. 611Apr 19, 1948 · 333 U.S. 611Federal taxation5–45–4 band
- United States Department of Agriculture, Emergency Crop and Feed Loans v. Remund, Administrator330 U.S. 539Mar 17, 1947 · 330 U.S. 539Federal taxation8–18–1 band
- Illinois ex rel. Gordon, Director of Labor, v. Campbell, Collector of Internal Revenue329 U.S. 362Dec 23, 1946 · 329 U.S. 362Federal taxation7–27–2 band
Data notes
Every other orally argued case with a clear vote, from the 1946 term on, that the Supreme Court Database files under the same issue as this one. The database gives each case one issue from a list of about 270 (abortion, search and seizure of vehicles, the death penalty, and so on), whatever law it turned on.
Official record
Read the full opinion on Justia and the argument audio on Oyez. Case data from the Supreme Court Database, Version 2026 Release 01, through the 2025 term.