Cammarano et ux. v. United States
The Court ruled that business may not deduct expenses they incurred for the "promotion or defeat of legislation" as "ordinary and necessary" business expenses on their federal income tax filing.
358 U.S. 498 · No. 29 · 1958 term · Warren Court
Decided Feb 24, 1959 · argued Nov 19, 1958
Federal taxation · Federal taxation of gifts, personal, business, or professional expenses
Majority opinion: John Harlan
The voteMajority
9–09 in the majority, 0 in dissent
No dissent (9–0)
Affirmed. Cammarano et ux. lost.
What this ruling means
Affirmed: the Supreme Court upheld the decision of the U.S. Court of Appeals, Ninth Circuit, so it stands (sometimes with changes the Court made to it).
Cammarano et ux. was the petitioner, the side that asked the Supreme Court to review the case. “Lost” means the Court did not give that side the result it asked for.
From the Supreme Court Database. A justice who agreed with the result but not the reasoning counts in the majority.
Summary
The opening of the case’s Wikipedia article: what the case was about and what the Court held.
Cammarano v. United States, 358 U.S. 498 (1959), was a United States Supreme Court case in which the Court ruled that business may not deduct expenses they incurred for the "promotion or defeat of legislation" as "ordinary and necessary" business expenses on their federal income tax filing.
Data notes
The text is Wikipedia’s (CC BY-SA 4.0), matched to the case by its citation, docket number or name and year, and is not checked against the opinion. The site keeps the article’s opening section, ending on its last full sentence. The one-sentence summary under the title is the Decisions list’s: Wikipedia’s own ruling sentence, or, tagged “AI-written”, one Claude wrote from this opening.
How the justices voted
Each justice who took part, placed by their Martin–Quinn ideology score for the 1958 term. Filled: the 9 in the majority. Hollow: the 0 in dissent. Colour is the party of the president who appointed them.
Majority(9)
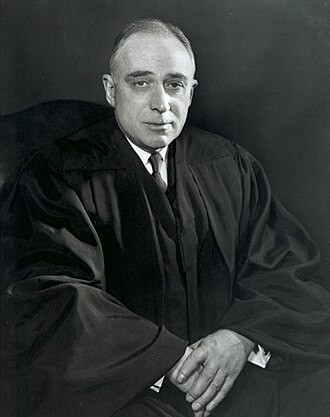 John HarlanWrote the majority opinion
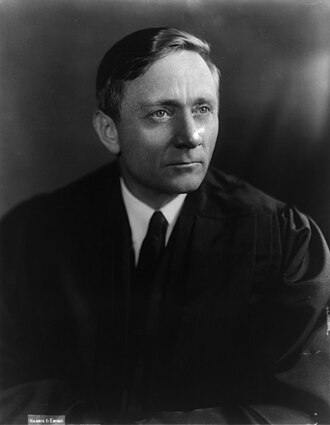 William DouglasWrote a concurrence
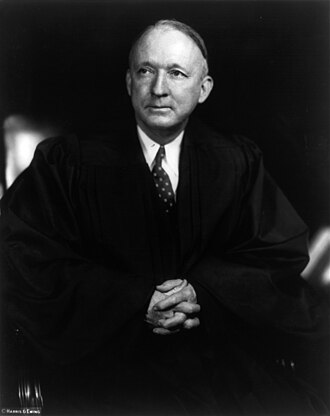 Hugo BlackJoined the majority
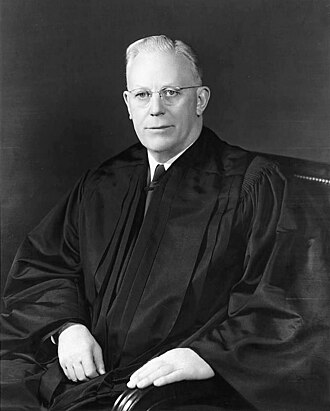 Earl WarrenJoined the majority
 William BrennanJoined the majority
 Tom ClarkJoined the majority
 Potter StewartJoined the majority
 Charles WhittakerJoined the majority
 Felix FrankfurterJoined the majority
Dissent(0)
- None.
Data notes
Each justice’s vote and what they wrote are from the justice-centered file of the Supreme Court Database. “Wrote a concurrence” means the justice sided with the majority and wrote separately; a justice who dissented in part is counted on the side they took overall. A justice who wrote nothing is listed as joining their side.
Positions are each justice’s Martin–Quinn score for the case’s term, the same scores as the Ideology page: negative is more liberal, positive more conservative. A score sums up a justice’s votes across the whole term, so it says where they usually sit, not why they voted as they did here. The median line is the Court’s median justice that term.
The parties
Who brought the case to the Court, who answered it, and how it got there.
- Petitioner
- Cammarano et ux.Taxpayer or executor of taxpayer's estate, federal only
- Respondent
- United StatesUnited States
- Reached the Court by
- Certiorari (the Court chose to hear it)
Data notes
The names are the two sides of the case’s title. The description under each is the Supreme Court Database’s category for that party, in its own wording. The petitioner is the side that asked the Supreme Court to review the decision below. “Why it was taken” appears only when the majority opinion says lower courts disagreed or were unsure about the question; reasons that would fit any case (“to resolve the question presented”, “an important question”) are left out.
The law at issue
The law the Court was asked to apply, and the kind of power it used to decide.
- Provision
- Internal Revenue Code and pre-IRC revenue acts
- Kind of law
- Federal Statute
- Decided by
- Statutory construction; Interpretation of administrative regulation or rule, or executive order
Data notes
The Supreme Court Database codes the main constitutional provision, statute or court rule each case turned on, and the basis of the decision: judicial review of a federal or state law, interpreting a statute, supervising the lower courts, and so on. A case can rest on more than one. “Overruled” counts only where the majority opinion says so.
Timeline
What happened at the Court and how the case got there, newest first.
- Feb 24, 1959DecidedDecided · Decided 9–0: affirmed. Cammarano et ux. lost.
- Nov 19, 1958ArguedArgued · Oral argument before the Court.
- Not datedTaken upTaken up · The Supreme Court agreed to hear the case (certiorari).
- Not datedCourt belowCourt below · Decided by the U.S. Court of Appeals, Ninth Circuit: affirmed.
- Not datedBeganBegan · The case began in the Washington Western U.S. District Court.
Data notes
From the Supreme Court Database: the court the case began in, the court whose decision the Supreme Court reviewed and what that court did, how the case came to the Court, and the dates of argument and decision. The database does not date the steps in the lower courts. Court names are the database’s.
Other decisions on the same issue
41 other argued cases since 1946 on federal taxation of gifts, personal, business, or professional expenses, newest first.
- Mayo Foundation for Medical Education and Research, et al., Petitioners v. United States562 U.S. 44Jan 11, 2011 · 562 U.S. 44Federal taxation8–0Unanimous band
- United States v. Abel Cosmo Galletti et al.541 U.S. 114Mar 23, 2004 · 541 U.S. 114Federal taxation9–0Unanimous band
- Commissioner of Internal Revenue v. Estate of Otis C. Hubert, Deceased, C & S Soveran Trust Company (Georgia) N. A., Co-Executor520 U.S. 93Mar 18, 1997 · 520 U.S. 93Federal taxation7–27–2 band
- United States v. John O. Irvine and First Trust National Association511 U.S. 224Apr 20, 1994 · 511 U.S. 224Federal taxation8–0Unanimous band
- Commissioner of Internal Revenue v. Nader E. Soliman506 U.S. 168Jan 12, 1993 · 506 U.S. 168Federal taxation8–18–1 band
- Indopco, Inc. v. Commissioner of Internal Revenue.503 U.S. 79Feb 26, 1992 · 503 U.S. 79Federal taxation9–0Unanimous band
- Davis et ux. v. United States495 U.S. 472May 21, 1990 · 495 U.S. 472Federal taxation9–0Unanimous band
- Hernandez v. Commissioner of Internal Revenue490 U.S. 680Jun 5, 1989 · 490 U.S. 680Federal taxation5–27–2 band
- United States et al. v. Hemme et al.476 U.S. 558Jun 3, 1986 · 476 U.S. 558Federal taxation9–0Unanimous band
- Dickman et al. v. Commissioner of Internal Revenue465 U.S. 330Feb 21, 1984 · 465 U.S. 330Federal taxation7–27–2 band
- Diedrich et al. v. Commissioner of Internal Revenue457 U.S. 191Jun 15, 1982 · 457 U.S. 191Federal taxation8–18–1 band
- Jewett et ux. v. Commissioner of Internal Revenue455 U.S. 305Feb 23, 1982 · 455 U.S. 305Federal taxation6–36–3 band
- United California Bank et al., Co-Executors v. United States439 U.S. 180Dec 11, 1978 · 439 U.S. 180Federal taxation6–36–3 band
- Central Illinois Public Service Co. v. United States435 U.S. 21Feb 28, 1978 · 435 U.S. 21Federal taxation9–0Unanimous band
- Commissioner of Internal Revenue v. Kowalski et ux.434 U.S. 77Nov 29, 1977 · 434 U.S. 77Federal taxation7–27–2 band
- Alexander, Commissioner of Internal Revenue v. 'Americans United' Inc.416 U.S. 752May 15, 1974 · 416 U.S. 752Federal taxation7–18–1 band
- Bob Jones University v. Simon, Secretary of the Treasury, et al.416 U.S. 725May 15, 1974 · 416 U.S. 725Federal taxation8–0Unanimous band
- United States v. Cartwright, Executor411 U.S. 546May 7, 1973 · 411 U.S. 546Federal taxation6–36–3 band
- United States v. Correll et ux.389 U.S. 299Dec 11, 1967 · 389 U.S. 299Federal taxation5–36–3 band
- Commissioner of Internal Revenue v. Stidger et ux.386 U.S. 287Mar 20, 1967 · 386 U.S. 287Federal taxation6–36–3 band
- Commissioner of Internal Revenue v. Tellier et ux.383 U.S. 687Mar 24, 1966 · 383 U.S. 687Federal taxation9–0Unanimous band
- United States v. Patrick et al.372 U.S. 53Feb 18, 1963 · 372 U.S. 53Federal taxation7–27–2 band
- United States v. Gilmore et ux.372 U.S. 39Feb 18, 1963 · 372 U.S. 39Federal taxation7–27–2 band
- Rudolph et ux. v. United States370 U.S. 269Jun 18, 1962 · 370 U.S. 269Federal taxation5–27–2 band
- United States v. Davis et al.370 U.S. 65Jun 4, 1962 · 370 U.S. 65Federal taxation7–0Unanimous band
- Commissioner of Internal Revenue v. Bilder, Executrix369 U.S. 499Apr 30, 1962 · 369 U.S. 499Federal taxation6–18–1 band
- Commissioner of Internal Revenue v. Lester366 U.S. 299May 22, 1961 · 366 U.S. 299Federal taxation9–0Unanimous band
- United States v. Kaiser363 U.S. 299Jun 13, 1960 · 363 U.S. 299Federal taxation6–36–3 band
- Commissioner of Internal Revenue v. Duberstein et ux.363 U.S. 278Jun 13, 1960 · 363 U.S. 278Federal taxation8–18–1 band
- Peurifoy et al. v. Commissioner of Internal Revenue358 U.S. 59Nov 10, 1958 · 358 U.S. 59Federal taxation6–36–3 band
- Fidelity-Philadelphia Trust Co. et al., Executors, v. Smith, Collector of Internal Revenue356 U.S. 274Apr 28, 1958 · 356 U.S. 274Federal taxation6–36–3 band
- United States v. Calamaro354 U.S. 351Jun 17, 1957 · 354 U.S. 351Federal taxation7–18–1 band
- Putnam et ux. v. Commissioner of Internal Revenue352 U.S. 82Dec 3, 1956 · 352 U.S. 82Federal taxation8–18–1 band
- Commissioner of Internal Revenue v. Estate of Sternberger, Chase National Bank of New York, Executor348 U.S. 187Jan 10, 1955 · 348 U.S. 187Federal taxation6–27–2 band
- Lober et al., Executors, v. United States346 U.S. 335Nov 9, 1953 · 346 U.S. 335Federal taxation7–27–2 band
- Robertson v. United States343 U.S. 711Jun 2, 1952 · 343 U.S. 711Federal taxation7–18–1 band
- Lykes v. United States343 U.S. 118Mar 24, 1952 · 343 U.S. 118Federal taxation6–36–3 band
- Lilly et al. v. Commissioner of Internal Revenue343 U.S. 90Mar 10, 1952 · 343 U.S. 90Federal taxation8–0Unanimous band
- Harris v. Commissioner of Internal Revenue340 U.S. 106Nov 27, 1950 · 340 U.S. 106Federal taxation5–45–4 band
- United States v. Benedict et al., Trustees, et al.338 U.S. 692Feb 13, 1950 · 338 U.S. 692Federal taxation5–36–3 band
- Henslee, Collector of Internal Revenue, v. Union Planters National Bank & Trust Co. et al.335 U.S. 595Jan 3, 1949 · 335 U.S. 595Federal taxation6–36–3 band
Data notes
Every other orally argued case with a clear vote, from the 1946 term on, that the Supreme Court Database files under the same issue as this one. The database gives each case one issue from a list of about 270 (abortion, search and seizure of vehicles, the death penalty, and so on), whatever law it turned on.
Official record
Read the full opinion on Justia, the argument audio on Oyez and Wikipedia. Case data from the Supreme Court Database, Version 2026 Release 01, through the 2025 term.