J. Elliott Hibbs, Director, Arizona Department of Revenue v. Kathleen M. Winn et al.
The court held that the Tax Injunction Act does not prevent a person from bringing a prospective challenge to the constitutionality of a tax credit assessed for other people.
542 U.S. 88 · No. 02-1809 · 2003 term · Rehnquist Court
Decided Jun 14, 2004 · argued Jan 20, 2004
Federalism · National supremacy: state tax
Majority opinion: Ruth Ginsburg
The voteMajorityDissent
5–45 in the majority, 4 in dissent
4 dissents (5–4)
Affirmed. J. Elliott Hibbs, Director, Arizona Department of Revenue lost.
What this ruling means
Affirmed: the Supreme Court upheld the decision of the U.S. Court of Appeals, Ninth Circuit, so it stands (sometimes with changes the Court made to it).
J. Elliott Hibbs, Director, Arizona Department of Revenue was the petitioner, the side that asked the Supreme Court to review the case. “Lost” means the Court did not give that side the result it asked for.
From the Supreme Court Database. A justice who agreed with the result but not the reasoning counts in the majority.
Summary
The opening of the case’s Wikipedia article: what the case was about and what the Court held.
Hibbs v. Winn, 542 U.S. 88 (2004), was a United States Supreme Court case in which the court held that the Tax Injunction Act does not prevent a person from bringing a prospective challenge to the constitutionality of a tax credit assessed for other people.
Data notes
The text is Wikipedia’s (CC BY-SA 4.0), matched to the case by its citation, docket number or name and year, and is not checked against the opinion. The site keeps the article’s opening section, ending on its last full sentence. The one-sentence summary under the title is the Decisions list’s: Wikipedia’s own ruling sentence, or, tagged “AI-written”, one Claude wrote from this opening.
How the justices voted
Each justice who took part, placed by their Martin–Quinn ideology score for the 2003 term. Filled: the 5 in the majority. Hollow: the 4 in dissent. Colour is the party of the president who appointed them.
Majority(5)
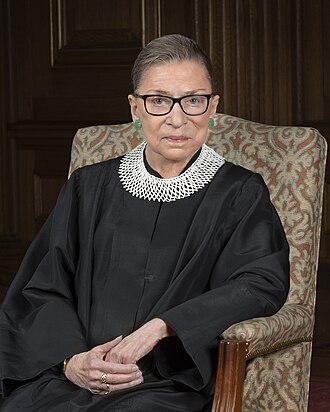 Ruth GinsburgWrote the majority opinion
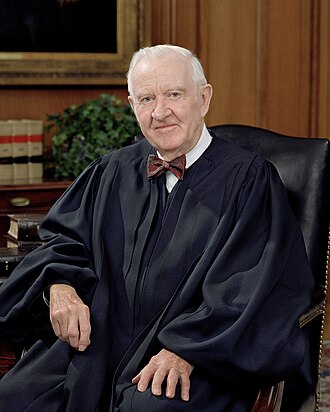 John StevensWrote a concurrence
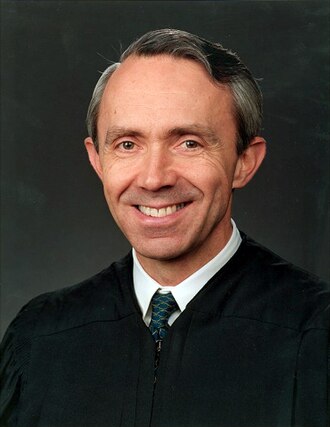 David SouterJoined the majority
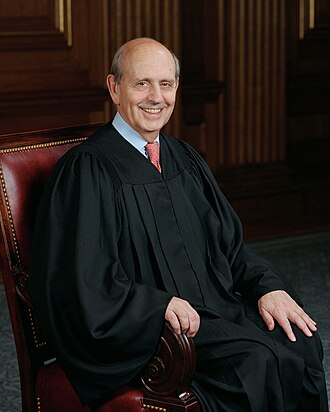 Stephen BreyerJoined the majority
 Sandra O'ConnorJoined the majority
Dissent(4)
 Anthony KennedyWrote a dissent
 William RehnquistJoined a dissent
 Antonin ScaliaJoined a dissent
 Clarence ThomasJoined a dissent
Data notes
Each justice’s vote and what they wrote are from the justice-centered file of the Supreme Court Database. “Wrote a concurrence” means the justice sided with the majority and wrote separately; a justice who dissented in part is counted on the side they took overall. A justice who wrote nothing is listed as joining their side.
Positions are each justice’s Martin–Quinn score for the case’s term, the same scores as the Ideology page: negative is more liberal, positive more conservative. A score sums up a justice’s votes across the whole term, so it says where they usually sit, not why they voted as they did here. The median line is the Court’s median justice that term.
The parties
Who brought the case to the Court, who answered it, and how it got there.
- Petitioner
- J. Elliott Hibbs, Director, Arizona Department of RevenueState department or agency (Arizona)
- Respondent
- Kathleen M. Winn et al.State or local governmental taxpayer, or executor of the estate (Arizona)
- Reached the Court by
- Certiorari (the Court chose to hear it)
- Why it was taken
- Federal appeals courts had ruled differently on the question
Data notes
The names are the two sides of the case’s title. The description under each is the Supreme Court Database’s category for that party, in its own wording. The petitioner is the side that asked the Supreme Court to review the decision below. “Why it was taken” appears only when the majority opinion says lower courts disagreed or were unsure about the question; reasons that would fit any case (“to resolve the question presented”, “an important question”) are left out.
The law at issue
The law the Court was asked to apply, and the kind of power it used to decide.
- Provision
- 28 U.S.C. § 1341
- Kind of law
- Infrequently litigated statutes
- Decided by
- Statutory construction
Data notes
The Supreme Court Database codes the main constitutional provision, statute or court rule each case turned on, and the basis of the decision: judicial review of a federal or state law, interpreting a statute, supervising the lower courts, and so on. A case can rest on more than one. “Overruled” counts only where the majority opinion says so.
Timeline
What happened at the Court and how the case got there, newest first.
- Jun 14, 2004DecidedDecided · Decided 5–4: affirmed. J. Elliott Hibbs, Director, Arizona Department of Revenue lost.
- Jan 20, 2004ArguedArgued · Oral argument before the Court.
- Not datedTaken upTaken up · The Supreme Court agreed to hear the case (certiorari). Federal appeals courts had ruled differently on the question.
- Not datedCourt belowCourt below · Decided by the U.S. Court of Appeals, Ninth Circuit: reversed.
- Not datedBeganBegan · The case began in the Arizona U.S. District Court.
Data notes
From the Supreme Court Database: the court the case began in, the court whose decision the Supreme Court reviewed and what that court did, how the case came to the Court, and the dates of argument and decision. The database does not date the steps in the lower courts. Court names are the database’s.
Other decisions on the same issue
12 other argued cases since 1946 on national supremacy: state tax, newest first.
- Dawson v. Steager139 S. Ct. 698Feb 20, 2019 · 139 S. Ct. 698Federalism9–0Unanimous band
- Arizona Department of Revenue v. Blaze Construction Company, Inc.526 U.S. 32Mar 2, 1999 · 526 U.S. 32Federalism9–0Unanimous band
- James B. Beam Distilling Co. v. Georgia et al.501 U.S. 529Jun 20, 1991 · 501 U.S. 529Federalism6–36–3 band
- Davis v. Michigan Department of the Treasury489 U.S. 803Mar 28, 1989 · 489 U.S. 803Federalism8–18–1 band
- United States Steel Corp. et al. v. Multistate Tax Commission et al.434 U.S. 452Feb 21, 1978 · 434 U.S. 452Federalism7–27–2 band
- United States et al. v. County of Fresno429 U.S. 452Jan 25, 1977 · 429 U.S. 452Federalism8–18–1 band
- United States v. State Tax Commission of Mississippi et al.412 U.S. 363Jun 4, 1973 · 412 U.S. 363Federalism7–27–2 band
- Sullivan, Tax Commissioner of Connecticut, et al. v. United States et al.395 U.S. 169May 26, 1969 · 395 U.S. 169Federalism8–0Unanimous band
- Department of Revenue v. James B. Beam Distilling Co.377 U.S. 341Jun 1, 1964 · 377 U.S. 341Federalism6–27–2 band
- Humble Pipe Line Co. v. Waggonner, Sheriff376 U.S. 369Mar 23, 1964 · 376 U.S. 369Federalism9–0Unanimous band
- Michigan National Bank et al. v. Michigan et al.365 U.S. 467Mar 6, 1961 · 365 U.S. 467Federalism6–27–2 band
- Phillips Chemical Co. v. Dumas Independent School District361 U.S. 376Feb 23, 1960 · 361 U.S. 376Federalism9–0Unanimous band
Data notes
Every other orally argued case with a clear vote, from the 1946 term on, that the Supreme Court Database files under the same issue as this one. The database gives each case one issue from a list of about 270 (abortion, search and seizure of vehicles, the death penalty, and so on), whatever law it turned on.
Official record
Read the full opinion on Justia, the argument audio on Oyez and Wikipedia. Case data from the Supreme Court Database, Version 2026 Release 01, through the 2025 term.