Commissioner of Internal Revenue v. Sunnen
In a dispute over the scope of collateral estoppel in federal tax liability, the Court said it must be confined to situations where the later matter is identical to the earlier one and the controlling facts and legal rules are unchanged.· AI-written
333 U.S. 591 · No. 227 · 1947 term · Vinson Court
Decided Apr 5, 1948 · argued Dec 17, 1947
Judicial power · Judicial administration: collateral estoppel or res judicata
Majority opinion: Frank Murphy
The voteMajority
9–09 in the majority, 0 in dissent
No dissent (9–0)
Reversed and remanded. Commissioner of Internal Revenue won.
What this ruling means
Reversed and remanded: the Supreme Court overturned the decision of the U.S. Court of Appeals, Eighth Circuit and sent the case back to that court for further proceedings that follow the Supreme Court’s ruling.
Commissioner of Internal Revenue was the petitioner, the side that asked the Supreme Court to review the case. “Won” means the Court gave that side the result it asked for.
From the Supreme Court Database. A justice who agreed with the result but not the reasoning counts in the majority.
Summary
The opening of the case’s Wikipedia article: what the case was about and what the Court held.
Commissioner v. Sunnen, 333 U.S. 591 (1948), was a case decided by the Supreme Court of the United States in 1948 in which the Court outlined the scope of collateral estoppel or estoppel by judgment in determinations of federal tax liability. This was important because a single controversial circumstance may have a bearing on income tax liability for several years. Res judicata, as part of the doctrine of judicial finality, protects a taxpayer's tax liability for a given year once the taxpayer wins a judgment in court. The judgment is controlling not only controlling with regard to the issues litigated but also with any issues that could have been raised if they would have affected the determination of tax liability for the year. However, of course, a single controversial circumstance may have a bearing on income tax liability for several years, and if a judgment fixes liability for one of the years, res judiciary forecloses the reopening of only that year's liability. But the related doctrine of collateral estoppel prevents relitigation of issues that were in fact raised and decided in the earlier litigation, even when they arise in a new cause of action, such as a dispute as to liability for a later year.
However, the Supreme Court said that collateral estoppel in determinations of tax liability "must be confined to situations where the matter raised in the second suit is identical in all respects with that decided in the first proceeding and where the controlling facts and applicable legal rules remain unchanged."
Data notes
The text is Wikipedia’s (CC BY-SA 4.0), matched to the case by its citation, docket number or name and year, and is not checked against the opinion. The site keeps the article’s opening section, ending on its last full sentence. The one-sentence summary under the title is the Decisions list’s: Wikipedia’s own ruling sentence, or, tagged “AI-written”, one Claude wrote from this opening.
How the justices voted
Each justice who took part, placed by their Martin–Quinn ideology score for the 1947 term. Filled: the 9 in the majority. Hollow: the 0 in dissent. Colour is the party of the president who appointed them.
Majority(9)
 Frank MurphyWrote the majority opinion
 Hugo BlackJoined the majority
 Wiley RutledgeJoined the majority
 William DouglasJoined the majority
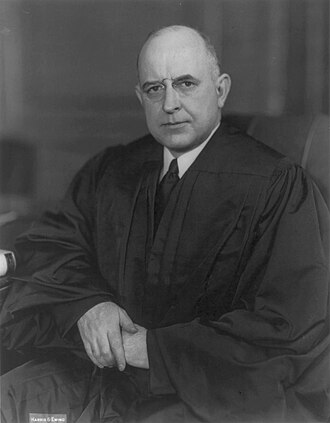 Stanley ReedJoined the majority
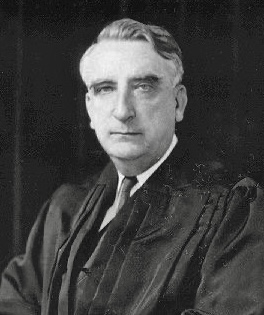 Frederick VinsonJoined the majority
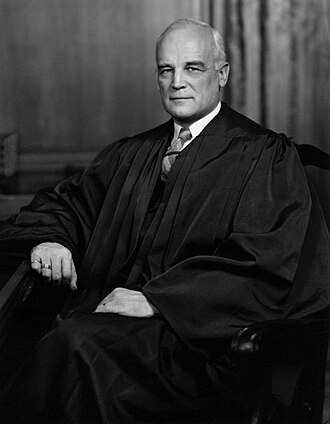 Harold BurtonJoined the majority
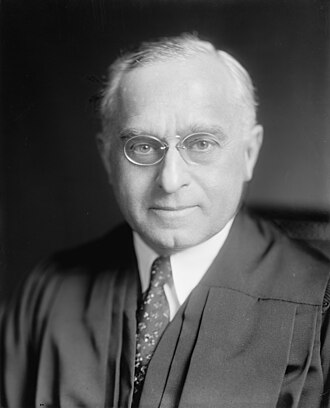 Felix FrankfurterJoined the majority
 Robert JacksonJoined the majority
Dissent(0)
- None.
Data notes
Each justice’s vote and what they wrote are from the justice-centered file of the Supreme Court Database. “Wrote a concurrence” means the justice sided with the majority and wrote separately; a justice who dissented in part is counted on the side they took overall. A justice who wrote nothing is listed as joining their side.
Positions are each justice’s Martin–Quinn score for the case’s term, the same scores as the Ideology page: negative is more liberal, positive more conservative. A score sums up a justice’s votes across the whole term, so it says where they usually sit, not why they voted as they did here. The median line is the Court’s median justice that term.
The parties
Who brought the case to the Court, who answered it, and how it got there.
- Petitioner
- Commissioner of Internal RevenueInternal Revenue Service, Collector, Commissioner, or District Director
- Respondent
- SunnenTaxpayer or executor of taxpayer's estate, federal only
- Reached the Court by
- Certiorari (the Court chose to hear it)
- Why it was taken
- Lower courts appeared to disagree
Data notes
The names are the two sides of the case’s title. The description under each is the Supreme Court Database’s category for that party, in its own wording. The petitioner is the side that asked the Supreme Court to review the decision below. “Why it was taken” appears only when the majority opinion says lower courts disagreed or were unsure about the question; reasons that would fit any case (“to resolve the question presented”, “an important question”) are left out.
The law at issue
The law the Court was asked to apply, and the kind of power it used to decide.
- Provision
- Estoppel
- Kind of law
- Other
- Decided by
- Federal common law
Data notes
The Supreme Court Database codes the main constitutional provision, statute or court rule each case turned on, and the basis of the decision: judicial review of a federal or state law, interpreting a statute, supervising the lower courts, and so on. A case can rest on more than one. “Overruled” counts only where the majority opinion says so.
Timeline
What happened at the Court and how the case got there, newest first.
- Apr 5, 1948DecidedDecided · Decided 9–0: reversed and remanded. Commissioner of Internal Revenue won.
- Dec 17, 1947ArguedArgued · Oral argument before the Court.
- Not datedTaken upTaken up · The Supreme Court agreed to hear the case (certiorari). Lower courts appeared to disagree.
- Not datedCourt belowCourt below · Decided by the U.S. Court of Appeals, Eighth Circuit: affirmed and reversed (or vacated) in part.
- Not datedBeganBegan · The case began in the U.S. Tax Court.
Data notes
From the Supreme Court Database: the court the case began in, the court whose decision the Supreme Court reviewed and what that court did, how the case came to the Court, and the dates of argument and decision. The database does not date the steps in the lower courts. Court names are the database’s.
Other decisions on the same issue
12 other argued cases since 1946 on judicial administration: collateral estoppel or res judicata, newest first.
- Keathley v. Buddy Ayers Construction146 S. Ct. 1532Jun 11, 2026 · 146 S. Ct. 1532Judicial power9–0Unanimous band
- Taylor v. Sturgell553 U.S. 880Jun 12, 2008 · 553 U.S. 880Judicial power9–0Unanimous band
- Semtek International Incorporated v. Lockheed Martin Corporation531 U.S. 497Feb 27, 2001 · 531 U.S. 497Judicial power9–0Unanimous band
- United States v. Stauffer Chemical Co.464 U.S. 165Jan 10, 1984 · 464 U.S. 165Judicial power9–0Unanimous band
- United States v. Mendoza464 U.S. 154Jan 10, 1984 · 464 U.S. 154Judicial power9–0Unanimous band
- Federated Department Stores, Inc., et al. v. Moitie et al.452 U.S. 394Jun 15, 1981 · 452 U.S. 394Judicial power8–18–1 band
- Parklane Hosiery Co., Inc., et al. v. Shore439 U.S. 322Jan 9, 1979 · 439 U.S. 322Judicial power8–18–1 band
- Ford v. Ford371 U.S. 187Dec 10, 1962 · 371 U.S. 187Judicial power9–0Unanimous band
- Callanan Road Improvement Co. v. United States et al.345 U.S. 507May 4, 1953 · 345 U.S. 507Judicial power8–18–1 band
- United States v. International Building Co.345 U.S. 502May 4, 1953 · 345 U.S. 502Judicial power9–0Unanimous band
- United States v. Munsingwear, Inc.340 U.S. 36Nov 13, 1950 · 340 U.S. 36Judicial power8–18–1 band
- Angel v. Bullington330 U.S. 183Feb 17, 1947 · 330 U.S. 183Judicial power6–36–3 band
Data notes
Every other orally argued case with a clear vote, from the 1946 term on, that the Supreme Court Database files under the same issue as this one. The database gives each case one issue from a list of about 270 (abortion, search and seizure of vehicles, the death penalty, and so on), whatever law it turned on.
Official record
Read the full opinion on Justia and Wikipedia. Case data from the Supreme Court Database, Version 2026 Release 01, through the 2025 term.